Category: Uncategorized

  • IIT Kanpur’s $1B Initiative: Can India’s Biggest Ever Campus Fund Bridge the AI Gap?

    IIT Kanpur has launched its massive campaign — “Greater Than Us” to gear up India’s pace in the AI race.
    The target is to raise $1 billion (~₹8,500+ crore) by March 2029 to bridge the gap between lab research and commercial deep tech.
    This is the largest institutional fundraising drive ever attempted by an Indian university, signaling a fundamental shift in how domestic deep tech gets financed.
    Early momentum backed by heavy alumni capital
    With the launch, it was announced that over ₹4,000 crore has already been committed, which shows that they have already been working silently with industry leaders for months, and it is not just another scheme launched by the government. One of the largest pledges of ₹180 crore has been made by Rahul Gautam (IIT kanpur alumni & Chairman of Sheela Foam, the company behind Sleepwell & Kurl-on).
    Merging the best global playbooks
    The model is perhaps inspired by very successful international frameworks: MIT’s “The Engine” and Stanford’s similar programs. They provide a patient capital that helps complex lab research to translate into market-ready commercial solution that have the potential to lead markets. To put some context, MIT’s The Engine manages a $1 billion fund and its 70 portfolio companies have raised over $11 billion from the market. Stanford takes it one step further—its historic capital campaign raised over $6 billion, helping nurture a cutting edge tech ecosystem whose companies have raised over 40 billions of dollars across different sectors.
    India too has seen a glimpse of what campus-led deep tech can produce. IIT Madras has been doing this quietly in the aerospace and robotics segment for quite some time, and we are now seeing companies like Agnikul Cosmos (3D-printed rocket engines), Ather, and The ePlane Company (electric flying taxis), to name a few. IIT Kanpur is taking this to a new scale and targeting semiconductors, AI, and quantum computing.
    A permanent shift toward self-sustaining innovation
    India spends roughly 0.65% of its GDP on R&D compared to 2.8% by China and 3.5% by the USA. That is 1/5th of the USA as a percentage of GDP. In absolute terms, the USA spends ~$800 billion vs. India’s $20–25 billion. This is just too low.
    In such a dearth of R&D spend, this $1 billion USD innovation focussed fund is not life-changing, but it is a step in the right direction.
    And the approach makes total sense. By pairing global philanthropy and private capital with one of India’s top tech institutes, it cuts reliance on government funding. It creates a self-sustaining system to turn lab research in AI, quantum tech, and med-tech into real commercial products right here in India.
  • Just How Big Is AI? I Tried Explaining It to My Wife

    Donald Trump has a new name for it – SI.

    Whatever you call it, AI has dominated more headlines than any other topic in the world for more than a year now.

    Despite hearing about it so often, I feel I know so little about it.

    How big is it REALLY?

    What are its different parts? How do they fit together?

    And why do I keep hearing people say that India has no real AI play?

    So, I did some research and put together a few pointers with two things in mind. They should be easy to understand and generally accurate.

    1. How big is AI?

    The AI market cap is currently around $25tn.

    For perspective, India’s annual GDP is roughly $4 trillion. China’s is around $20 trillion.

    While this is not an apples-to-apples comparison, it can be said that the only economy larger than the AI economy right now is the USA.

    That is the crazy scale.

    And when we realise that all this has happened in last 2-3 years.

    That is the crazy rate of growth.

    So what exactly is happening in something that is so massive?

    2. Frontend of the Miracle = AI Labs & LLMs

    At the front end are AI labs such as OpenAI and Anthropic.

    These make LLMs like ChatGPT and Claude. (LLM = Large Language Model)

    These companies develop the models that power AI tools or magic tool that is leading this miracle.

    But these AI labs or LLMs need other components to work.

    3. Parts = GPUs & Memory

    Think of it this way. A program needs a computer to run. A computer has processors and memory to run on.

    AI models work on more or less same basic principle, but at a vastly larger scale. Remember $25tn?

    This is where GPUs and memory come in.

    GPUs are specialised processors that handle the massive calculations required to run AI models.

    NVIDIA is the dominant name in GPUs.

    And it went from being the 800th most valuable company in 2015 to the #1 most valuable company in 2025.

    But NVIDIA does not manufacture all its chips itself.

    It relies on manufacturers such as Taiwan’s TSMC and memory makers such as South Korea’s SK Hynix.

    How big is Hynix? Hynix is now valued at 25% of the ENTIRE SOUTH KOREAN stock market.

    Crazy scale. Crazy rate of growth.

    4. Aggregators of These Parts (or Hyperscalers)

    So we have the processors, RAM & the program. But no computer yet.

    Here come the companies that buy vast quantities of computing hardware from NVIDIA, connect then using sophisticated code and rent this enormous computing power out to AI labs.

    These are the existing cloud companies: Microsoft, Amazon and Google.

    These are now called hyperscalers (reminding again of crazy rate of growth)

    Why? Because much of the money being pumped into AI infrastructure comes from these companies.

    Why? Because they are some of the most cash-rich companies in the world.

    Why are other cash-rich companies, say oil companies, do this? Because it requires sophisticated expertise to prepare these supercomputers which they learnt in their cloud business.

    Hence, the hyperscalers are usually cloud giants.

    And it is these hyperscalers that are leading the crazy rate of growth.

    5. Where Is All of This Magic Happening?

    So, we have the program, the computer, the processors, memory, everything. Whats left?

    Office. Or Home. Whatever you like to call.

    These mega computing systems need a place to operate. Power to run on. That home is a data centre.

    A data centre is a facility that houses all these computing hardware, networking equipment and other infrastructure.

    This where LLMs are training 24×7.

    On the data fed by peoples usage.

    This is where this scary monster becomes more scary.

    6. More On Data Centers

    Data centers need three things in principle and in enormous quantities:

    • Land to build the facility.
    • Reliable electricity to run the machines.
    • Cooling systems to prevent the equipment from overheating.

    This creates another business opportunity.

    While it may sound like just another cog, remember that the monster machine is worth $25tn. Every tiny cog is worth billions here.

    So, how big are data centres?

    $500bn. For reference, the global mobile phone market, including Apple, Android and others, is worth $600bn.

    And this is where India wants to get its foot in the door.

    7. Where does India stand in Data Centers?

    The global Data Center Capacity is roughly 100GW.

    USA is 40GW. China 25GW. Inida is 1.5GW.

    So, India does not have scale yet. But it has rate of growth.

    India is targetting 2GW capacity by 2026 end.

    While USA & China are expnading Data center at annual 10-15%, India is aiming 20-25%.

    Which may put it in top 5 countries by 2030.

    8. Why India thinks it has a shot at this?

    Some of the factors that work in India’s favor.

    1] Data center needs data. Large population, cheap data, means one of largest data producing country. So a data processing centre here just makes sense.

    2] Data center needs power to run on. Cheaper the power, more attractive the business.

    While India’s power is neither cheap or expensive historivcally.

    But the recent solar power explosion in India is producing one of world’s cheapest powers. Some say, absolute cheapest.

    These factors could make India attractive for data centre investments.

    Then there are challenges.

    9. The first problem: Power

    Data centers need cheap power 24×7.

    India’s solar gives cheap power. But not 24×7.

    To make it 24×7, we need batteries. Batteries are not cheap.

    So the promise of cheap power starts to get weakened here.

    10. The second problem: Heat

    A computer generates heat when it operates.

    AI super computers or super servers, generate enormous amounts of heat.

    Just like everything else, because of this massive scale traditional cooling systems are becoming insufficient for some high-density AI workloads.

    New solutions are needed. Companies are experimenting with new technologies, specially liquid cooled technologies.

    Now consider India.

    Many parts of the country already experience extremely high temperatures. Cooling data centres in these conditions can require more energy compared to other parts of the world.

    Water is scarce. So that makes using liquid cooled technologies, being used in other parts of the world, difficult.

    So the economics get worse here.

    5. So, does India have an AI play?

    So we saw how AI has multiple cogs – LLMs, hyperscalers, GPU & memory makers, Data centers and so on.

    India may does not have a strong players in any of the layers yet.

    Even in Data Centers, we have around 1-2% of global capacity, with a population of of around 18%. Thats not great.

    And hence the upside as well. India is one of largest data producers. So, if planned well, India can not only have a good footing in Data Centers but in other layers as well.

    While the news overload of news might make it seem that we are on the peak of AI, this new era has just started and it has many hundreds of years to come.

  • Grip Invest Review: ₹2 Crore of Real Bond Investments Across 246 Transactions

    I have been investing in bonds and other fixed-income products for about three years, and I have slowly increased my allocation over that time.

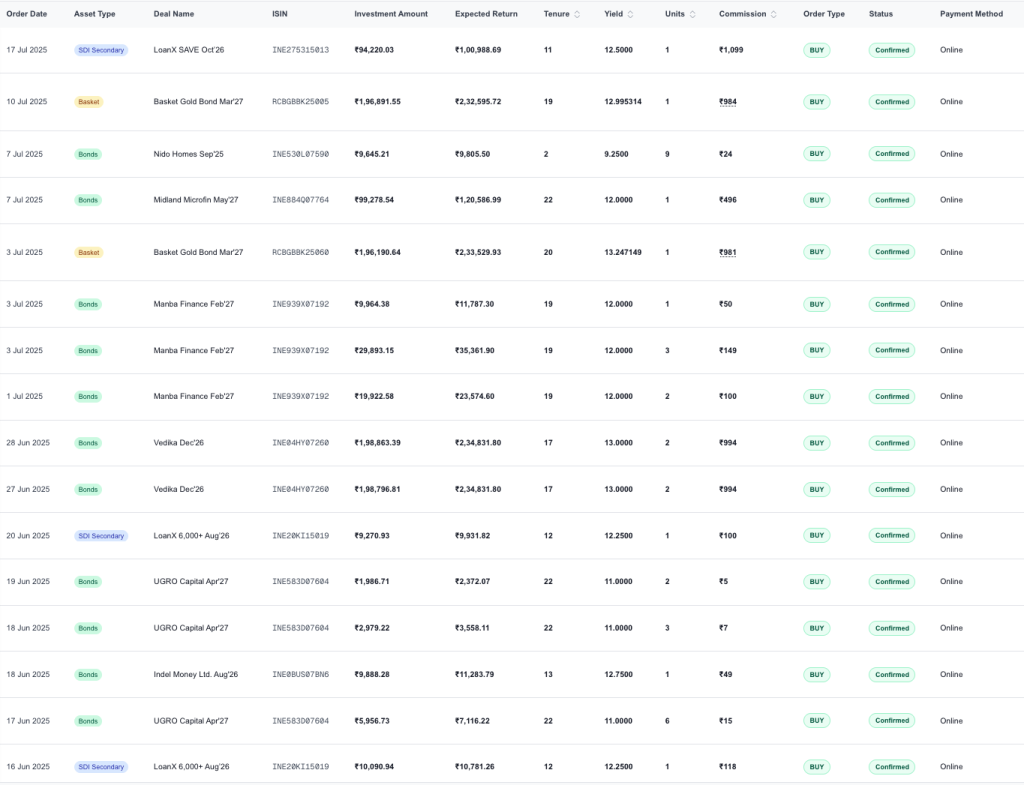
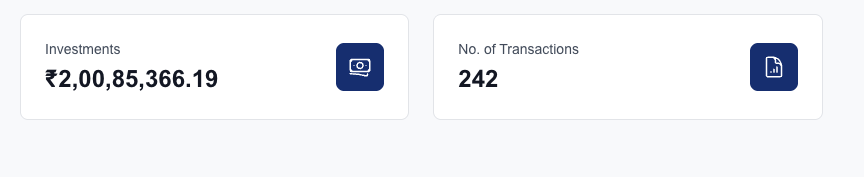
    Platforms publish the information they want you to see. Data from real investors gives another view, and I have access to over ₹2 crore worth of investments in bonds. This data covers the real investments of 25 investors and almost 250 transactions made through my affiliate code over about two years. The transactions include bonds, SDIs, FDs and other products, from different issuers, ratings and tenures, ranging from about four months to 36 months.

    Disclosure: Through my videos and blog, I work as an affiliate for Grip Invest and other investment platforms. When someone registers or invests with my code, their returns and terms don’t change, but I may earn a benefit. This is not my personal ₹2 crore portfolio. My referral links are at the end.

    This is a small sample and not a scientific study, so it can’t give a complete picture of bond investing. But I think it is large enough to be a good starting point for someone looking to invest in bonds or Grip Invest.

    What the Data Shows

    1. Average Investment Size – The median transaction is about ₹60,000 and the average is about ₹84,000. Transactions above ₹1 lakh are only about 27% of the count.

    2. Average Investment Period – The median tenure is 19 months, and about 25% of the investments run 24 months or longer. So this is not short-term parking.

    3. Most people take more yield than I do – About 75% of transactions have yields between 11% and 14%, and the median is 12.8%. My own investments are mostly in the 10.5–11% range, because I care more about credit quality and protecting principal than squeezing out the last bit of return.

    4. Bonds dominate, and SDIs have faded – About 70% of the money is in bonds. SDIs were about 91% of the money invested in mid-2024, but only 2–7% from late 2025 through mid-2026. After the three SDI-related issues I mention below, the platform started offering fewer of them and investors became more cautious. By the way, I still invest in SDIs when one fits my risk criteria.

    5. People diversify, and they hold – The investments are spread across roughly 60 issuers, and no single issuer takes more than about 6.5% of the money. Sell transactions are under 5% of what was bought. Most people hold to maturity, so treat any bond as locked-in money and early exit as a backup option.

    What the Data Can’t Tell Us

    I can see what people invested in, how much, for how long and in which products. What I can’t see is how many of these investments were delayed, defaulted or lost money. I don’t have an independent database for that.

    For issues, I rely solely on conversations with investors and the Grip Invest team.

    Over the past year, I am aware of three events involving delays, defaults or losses. They deserve their own discussion, so I covered them in a separate video or blog post.

    The point to remember is that fixed income is not risk-free income. Delays and defaults happen, and in some cases investors lose money.

    The data is also young. About 80% of these transactions happened in the last 15 months, and with a median tenure of 19 months, most of these investments haven’t matured yet. A clean record so far is encouraging, but it isn’t proof.

    What Has Happened to My Own Investments

    So far, none of my own investments have gone bad, been delayed or defaulted.

    I would be careful about what that means. It could partly be the way I select investments, but I may also have been lucky. It doesn’t mean my investments can’t go bad later, and it doesn’t mean bonds are safe. My experience has made me more comfortable with the asset class while keeping me cautious.

    How Do I Invest in Bonds

    I follow two basic rules.

    1. I don’t chase the highest return.
    I prefer higher-rated bonds, mainly A and AA-rated ones, and I don’t go down the rating scale just because something offers more. Earning 10% is fine for me. I am not trying to make 12–13% if it means taking much more credit risk. My main goal is not losing principal, and returns come second. This may not suit everyone, but it makes sense to me.

    2. I diversify.
    If I have ₹10 lakh to invest, I would rather spread it across something like 10 investments than put a very large amount into two or three. Even high-rated bonds carry issuer and credit risk. Diversification doesn’t remove that risk, but it stops one investment from becoming too large a part of your portfolio.

    If You’re New to Bonds, Start Small

    This is the biggest thing I would tell someone just starting. Don’t begin with a huge amount, even if you feel confident. Confidence is often what gets investors into trouble.

    The minimum investment in many products is around ₹10,000, so ₹1 lakh can be spread across several investments. Use your first ₹1 lakh, or whatever amount you are comfortable with, to learn how the whole process works:

    • How do interest payments arrive?
    • What happens at maturity?
    • What happens when an investment is delayed?
    • How do you track everything?
    • How does taxation work?

    These are much easier to understand with real experience than by reading about them. I would rather see a new investor spend the first six to twelve months learning how the asset class works than chasing the maximum return. Once you understand it better, you can decide whether to increase your allocation.

    Why I Keep Increasing My Fixed-Income Allocation

    I am quite happy that I took bonds and fixed income seriously. During the strong stock market of 2023–24, there was a lot of excitement around equities. I am glad I didn’t put a large part of my money there just because everyone around me was doing it.

    Also, my portfolio isn’t only bonds. I also hold FDs, debt funds, equities and other investments. Slowly, bonds have become a meaningful part of my fixed-income allocation, and as I have become more comfortable with them, I have increased it gradually. Just as I keep adding to my stocks or mutual funds, I add to fixed income every month or every few months, depending on what looks attractive and fits my overall portfolio.

    What I Think After 2–3 Years

    I don’t think there is a simple answer to whether bonds are a good investment. I am not telling you to invest, and I am not telling you they are safe. They aren’t.

    I started with a skeptical mindset, and I am still skeptical. Even with none of my own investments going bad so far, I approach every investment assuming something can go wrong. Your risk tolerance, finances and strategy may be completely different from mine.

    If you take only a few things from this article, take these:

    • Treat high-yield instruments as a reason to do more homework, not as a bargain.
    • Spread your money across issuers, and don’t let any one bond get too large.
    • Assume you will hold to maturity.
    • Start small and learn the process before you scale up.

    A Note About My Affiliate Link

    If you decide to explore Grip Invest, you can register through my affiliate link or code. It helps me financially and supports the content I create. You can also register just to look around, because there is no reason to invest until you are comfortable.

    My aim is simple: share the data I have and my own experience, be clear about what I don’t know, and leave the decision to you.

    Opening a new account? Consider my referral links. They help me make honest videos, and they have no impact on your returns.

    • WINT: Use code C4EAEB or this link
    • Grip Invest: Link
    • Altgraaf: Use code BH8922 or this link
    • Gullak: Use code 30Y99M or this link
    • Tap / Ultra: Use code X72D1Y


    Investment Disclosure

    I am not a SEBI-registered investment adviser or financial professional. This article is based on my personal experience and the data available to me, and is shared for informational purposes only. It should not be considered investment advice or a recommendation to buy or sell any investment. Please do your own research and consider your financial situation and risk tolerance before investing.